(204) 293-4305 aaleshka@sterlingmutuals.com
Adam Aleshka
  • HOME
  • ABOUT
    • ABOUT
    • FAQs
    • SUPPLIERS
    • PRIVACY STATEMENT &
      WEBSITE TERMS OF USE
  • SERVICES
    • FINANCIAL ADVICE
    • FINANCIAL ADVICE FOR
      BUSINESS OWNERS
    • FINANCIAL ADVICE FOR
      PROFESSIONALS
    • INSURANCE PLANNING
      • LIFE INSURANCE
      • CRITICAL ILLNESS INSURANCE
    • INVESTMENT PLANNING
      • PLANNING PYRAMID
      • YOUR RETIREMENT GOALS
      • SAVING & INVESTING
      • TFSAs
      • RRSPs
      • RRIFs
      • RESPs
      • FHSAs
      • RDSPs
  • RESOURCES
    • RESOURCES
    • CALCULATORS
    • Client Login
  • CLIENT LOGIN
  • BLOG
  • CONTACT
  • BOOK A MEETING
Select Page

Retirement Planning for Incorporated Professionals

by Investing with Purpose | Apr 1, 2020 | Blog, Corporate, Health Benefits, incorporated professionals, Life Insurance, Long Term Care, Pension Plan, RRSP, Tax Free Savings Account

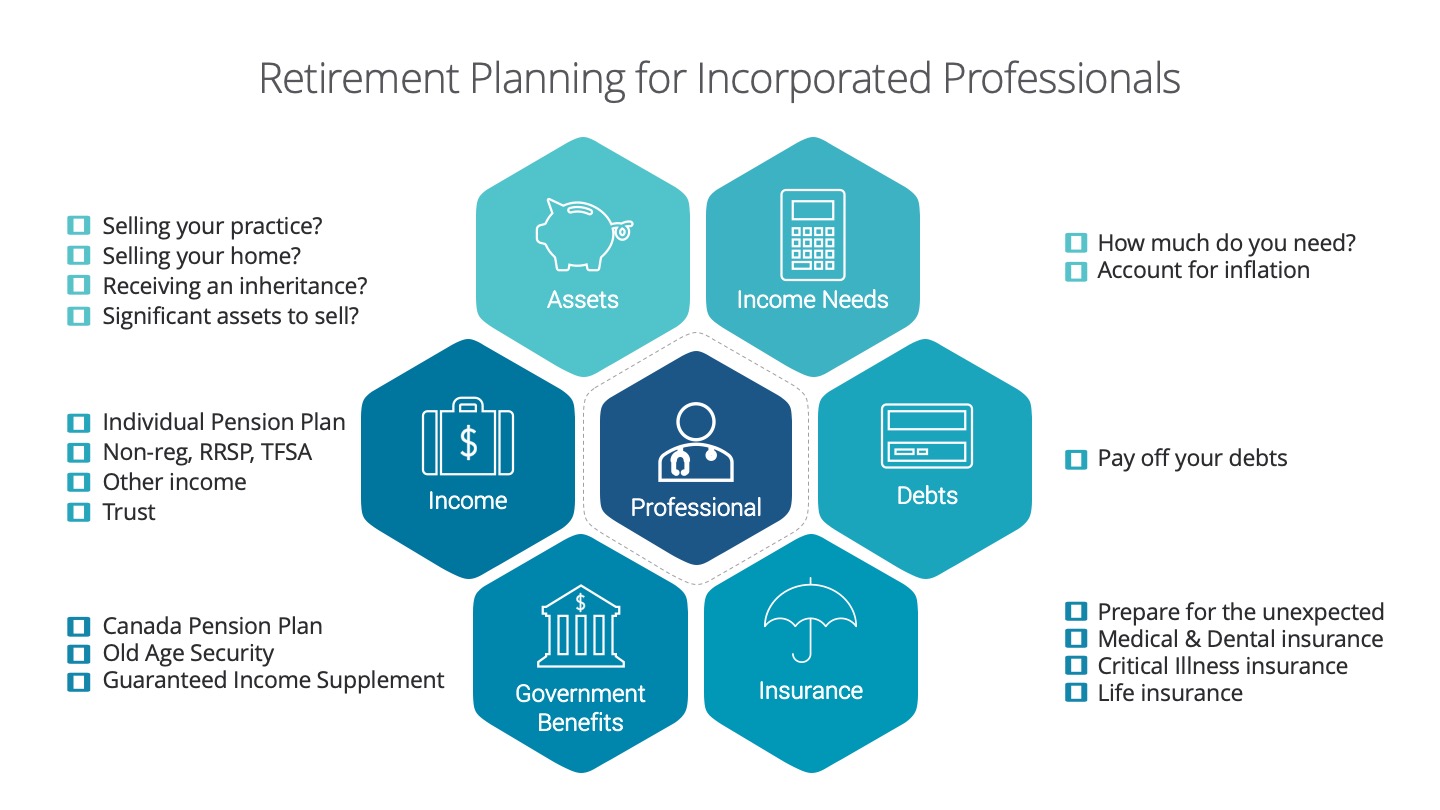
For incorporated professionals, preparing for retirement can go beyond finances, one of the biggest challenges is concern for the future of their clients or patients. Planning for retirement can take several advisors including a financial advisor, tax specialist and lawyer to help make the best decisions for their practice.

We’ve put together an infographic checklist that can help you get started on this. We know this can be a difficult conversation so we’re here to help and provide guidance to help you achieve your retirement dreams.

Income Needs

  • Determine how much you need in retirement.

  • Make sure you account for inflation in your calculations

Debts

  • If you have any debts, you should try to pay off your debts as soon as you can and preferably before you retire.

Insurance

  • As you age, your insurance needs change. Review your insurance needs, in particular your medical and dental insurance because a lot of plans do not provide health plans to retirees.

  • Review your life insurance coverage because you may not necessarily need as much life insurance as when you had dependents and a mortgage, but you may still need to review your estate and final expense needs.

  • Prepare for the unexpected such as a critical illness or long-term care.

Government Benefits

  • Check what benefits are available for you on retirement.

  • Canada Pension Plan- decide when would be the ideal time to apply and receive CPP payment. Incorporated professionals are in a unique position to control how much can be contributed to CPP by deciding to pay salary or dividends. (Dividends don’t trigger CPP contributions.)

  • Old Age Security- check pension amounts and see if there’s a possibility of clawback.

  • Guaranteed Income Supplement- if you client have a low income, you could apply for GIS.

Income

  • Are you a candidate for an individual pension plan (IPP)? IPPs can provide higher contributions than typically permitted to an RRSP and the ability to create a lifelong pension.

  • Make sure you are saving on a regular basis towards retirement- in an RRSP, TFSA, or non-registered. Since you can control how you get paid, salary or dividends, dividends are not considered eligible income to create RRSP room, therefore you should make sure you have the optimal mix of both to achieve your financial goals.

  • Ensure your investment mix makes sense for your situation.

  • Are you a candidate for setting up a trust? Trusts are useful tools for paying less taxes, transfer of wealth and to control and protect assets.

  • Don’t forget to check if there are any income sources.  (ex. rental income, side hustle income, etc.)

Assets

  • The sale of your practice can be part of your retirement nest egg. Therefore, you should make sure you know the valuation of your practice and your plan to sell the practice to your family, employees, partners or a third party. You should also know when you decide to sell your practice too. For medical professionals, understanding the value of your practice can be a little different since the valuation of patient lists and goodwill will differ from assets (such as medical equipment, fixtures and furniture.)Are you planning to use the sale of your home or other assets to fund their retirement?

  • Are you planning to use the sale of your home or other assets to fund their retirement?

  • Will you be receiving an inheritance?

One other consideration that’s not included in the checklist is divorce. This can be an uncomfortable question, however divorce amongst adults ages 50 and over is on the rise and this can be financially devastating for both parties.

Next steps…

  • Contact us about helping you get your retirement planning in order so you can gain peace of mind that your retirement dreams can be achieved.

Latest posts

  • Why a Critical Illness Insurance Top-Up Could Make a Big Difference

    Why a Critical Illness Insurance Top-Up Could Make a Big Difference

    September 1, 2026
  • Financial Checklist for New Parents in Canada

    Financial Checklist for New Parents in Canada

    August 3, 2026
  • How to Catch Up on Your RRSP Contributions

    How to Catch Up on Your RRSP Contributions

    June 30, 2026
  • What Is Participating Whole Life Insurance?

    What Is Participating Whole Life Insurance?

    June 1, 2026
  • Tax-Free Savings Account vs Registered Retirement Savings Plan

    Tax-Free Savings Account vs Registered Retirement Savings Plan

    June 1, 2026

RSS Subscribe via RSS

  • Why a Critical Illness Insurance Top-Up Could Make a Big Difference September 1, 2026
    Many Canadians have some critical illness coverage through work, but it often isn’t enough. A top-up can help families, employees, and business owners bridge the gap, offering peace of mind, flexibility, and protection when it’s needed most.
    Investing with Purpose
  • Financial Checklist for New Parents in Canada August 3, 2026
    A new baby changes everything, including your money. Between sleepless nights and tiny socks, a few financial steps can help protect your growing family. Here is a simple checklist of what to set up, update, and start when a baby joins your home.
    Investing with Purpose
  • How to Catch Up on Your RRSP Contributions June 30, 2026
    Unused RRSP contribution room does not disappear, it carries forward every year. If you have fallen behind on contributions, you may have more room than you realize. Here is how RRSP catch-up contributions work and how to use them to reduce your tax bill
    Investing with Purpose
  • What Is Participating Whole Life Insurance? June 1, 2026
    Participating whole life insurance is a permanent policy that does more than protect your family — it builds cash value and pays dividends over time. Learn how it works, who it's for, and how it compares to other types of life insurance.
    Investing with Purpose
  • Tax-Free Savings Account vs Registered Retirement Savings Plan June 1, 2026
    Tax-Free Savings Accounts (TFSAs) and Registered Retirement Savings Plans (RRSPs) are two of the most effective tools Canadians can use to save tax-efficiently. While TFSAs offer tax-free growth and flexible access, RRSPs provide tax-deductible contributions and tax-deferred growth. Understanding how each account works — and how withdrawals affect taxes and benefits — can help you […]
    Investing with Purpose

Mutual Funds Provided Through Sterling Mutuals Inc.

Insurance products and other related financial services are provided by Adam Aleshka & Investing With Purpose Ltd. as independent insurance agents and are not the business of or monitored by Sterling Mutuals Inc.

Investing With Purpose Ltd.

Adam Aleshka

Financial Advisor

BOOK A MEETING
To book a meeting with Adam please click the button above and book a phone call, virtual appointment or an in person meeting with Adam by accessing his online booking calendar.

The contents of this website do not constitute an offer or solicitation for residents in the United States or any other jurisdiction where Sterling Mutuals is not registered or permitted to conduct business.

Get In Touch



(204) 293-4305



Toll-Free

1-866-519-4301



aaleshka@sterlingmutuals.com



Suite 303 – 400 Wardlaw Avenue
Winnipeg, MB
R3L 0L7

  • Follow

Latest News

Why a Critical Illness Insurance Top-Up Could Make a Big Difference

Many Canadians have some critical illness coverage through work, but it often isn’t enough. A top-up can help families, employees, and business owners bridge the gap, offering peace of mind, flexibility, and protection when it’s needed most.

Financial Checklist for New Parents in Canada

A new baby changes everything, including your money. Between sleepless nights and tiny socks, a few financial steps can help protect your growing family. Here is a simple checklist of what to set up, update, and start when a baby joins your home.

How to Catch Up on Your RRSP Contributions

Unused RRSP contribution room does not disappear, it carries forward every year. If you have fallen behind on contributions, you may have more room than you realize. Here is how RRSP catch-up contributions work and how to use them to reduce your tax bill

What Is Participating Whole Life Insurance?

Participating whole life insurance is a permanent policy that does more than protect your family — it builds cash value and pays dividends over time. Learn how it works, who it’s for, and how it compares to other types of life insurance.

About Us

I think that the advisor/client partnership should be built on more than just “dollars and cents.” I feel as though it should be built upon mutual trust & transparency.  I feel as though the stronger our relationship is, the more likely it is that my clients will achieve their long term financial goals. I am seeking out more than just a typical transactional relationship with the families that I represent. I am seeking out long term partnerships with families committed to their long term financial success.

Legal Information

 Privacy Information

How to Make a Complaint

Investor Protection Corporation

Account Opening Information

2023© Financial Tech Tools Inc.