(204) 293-4305 aaleshka@sterlingmutuals.com
Adam Aleshka
  • HOME
  • ABOUT
    • ABOUT
    • FAQs
    • SUPPLIERS
    • PRIVACY STATEMENT &
      WEBSITE TERMS OF USE
  • SERVICES
    • FINANCIAL ADVICE
    • FINANCIAL ADVICE FOR
      BUSINESS OWNERS
    • FINANCIAL ADVICE FOR
      PROFESSIONALS
    • INSURANCE PLANNING
      • LIFE INSURANCE
      • CRITICAL ILLNESS INSURANCE
    • INVESTMENT PLANNING
      • PLANNING PYRAMID
      • YOUR RETIREMENT GOALS
      • SAVING & INVESTING
      • TFSAs
      • RRSPs
      • RRIFs
      • RESPs
      • FHSAs
      • RDSPs
  • RESOURCES
    • RESOURCES
    • CALCULATORS
    • Client Login
  • CLIENT LOGIN
  • BLOG
  • CONTACT
  • BOOK A MEETING
Select Page

TFSA vs RRSP – 2024

by Investing with Purpose | Feb 1, 2024 | 2024, Blog, Business Owners, Estate Planning, Family, financial advice, financial planning, Individuals, Investment, personal finances, Professionals, Retirement, RRSP, Tax Free Savings Account

Tax-Free Savings Account vs Registered Retirement Savings Plan

When looking to save money in a tax-efficient manner, Tax-Free Savings Accounts (TFSA) and Registered Retirement Savings Plans (RRSP) can offer significant tax benefits. To assist you in understanding the distinctions, we will compare the following:

  • The differences in deposits between TFSAs and RRSPs

  • The differences in withdrawals between TFSAs and RRSPs
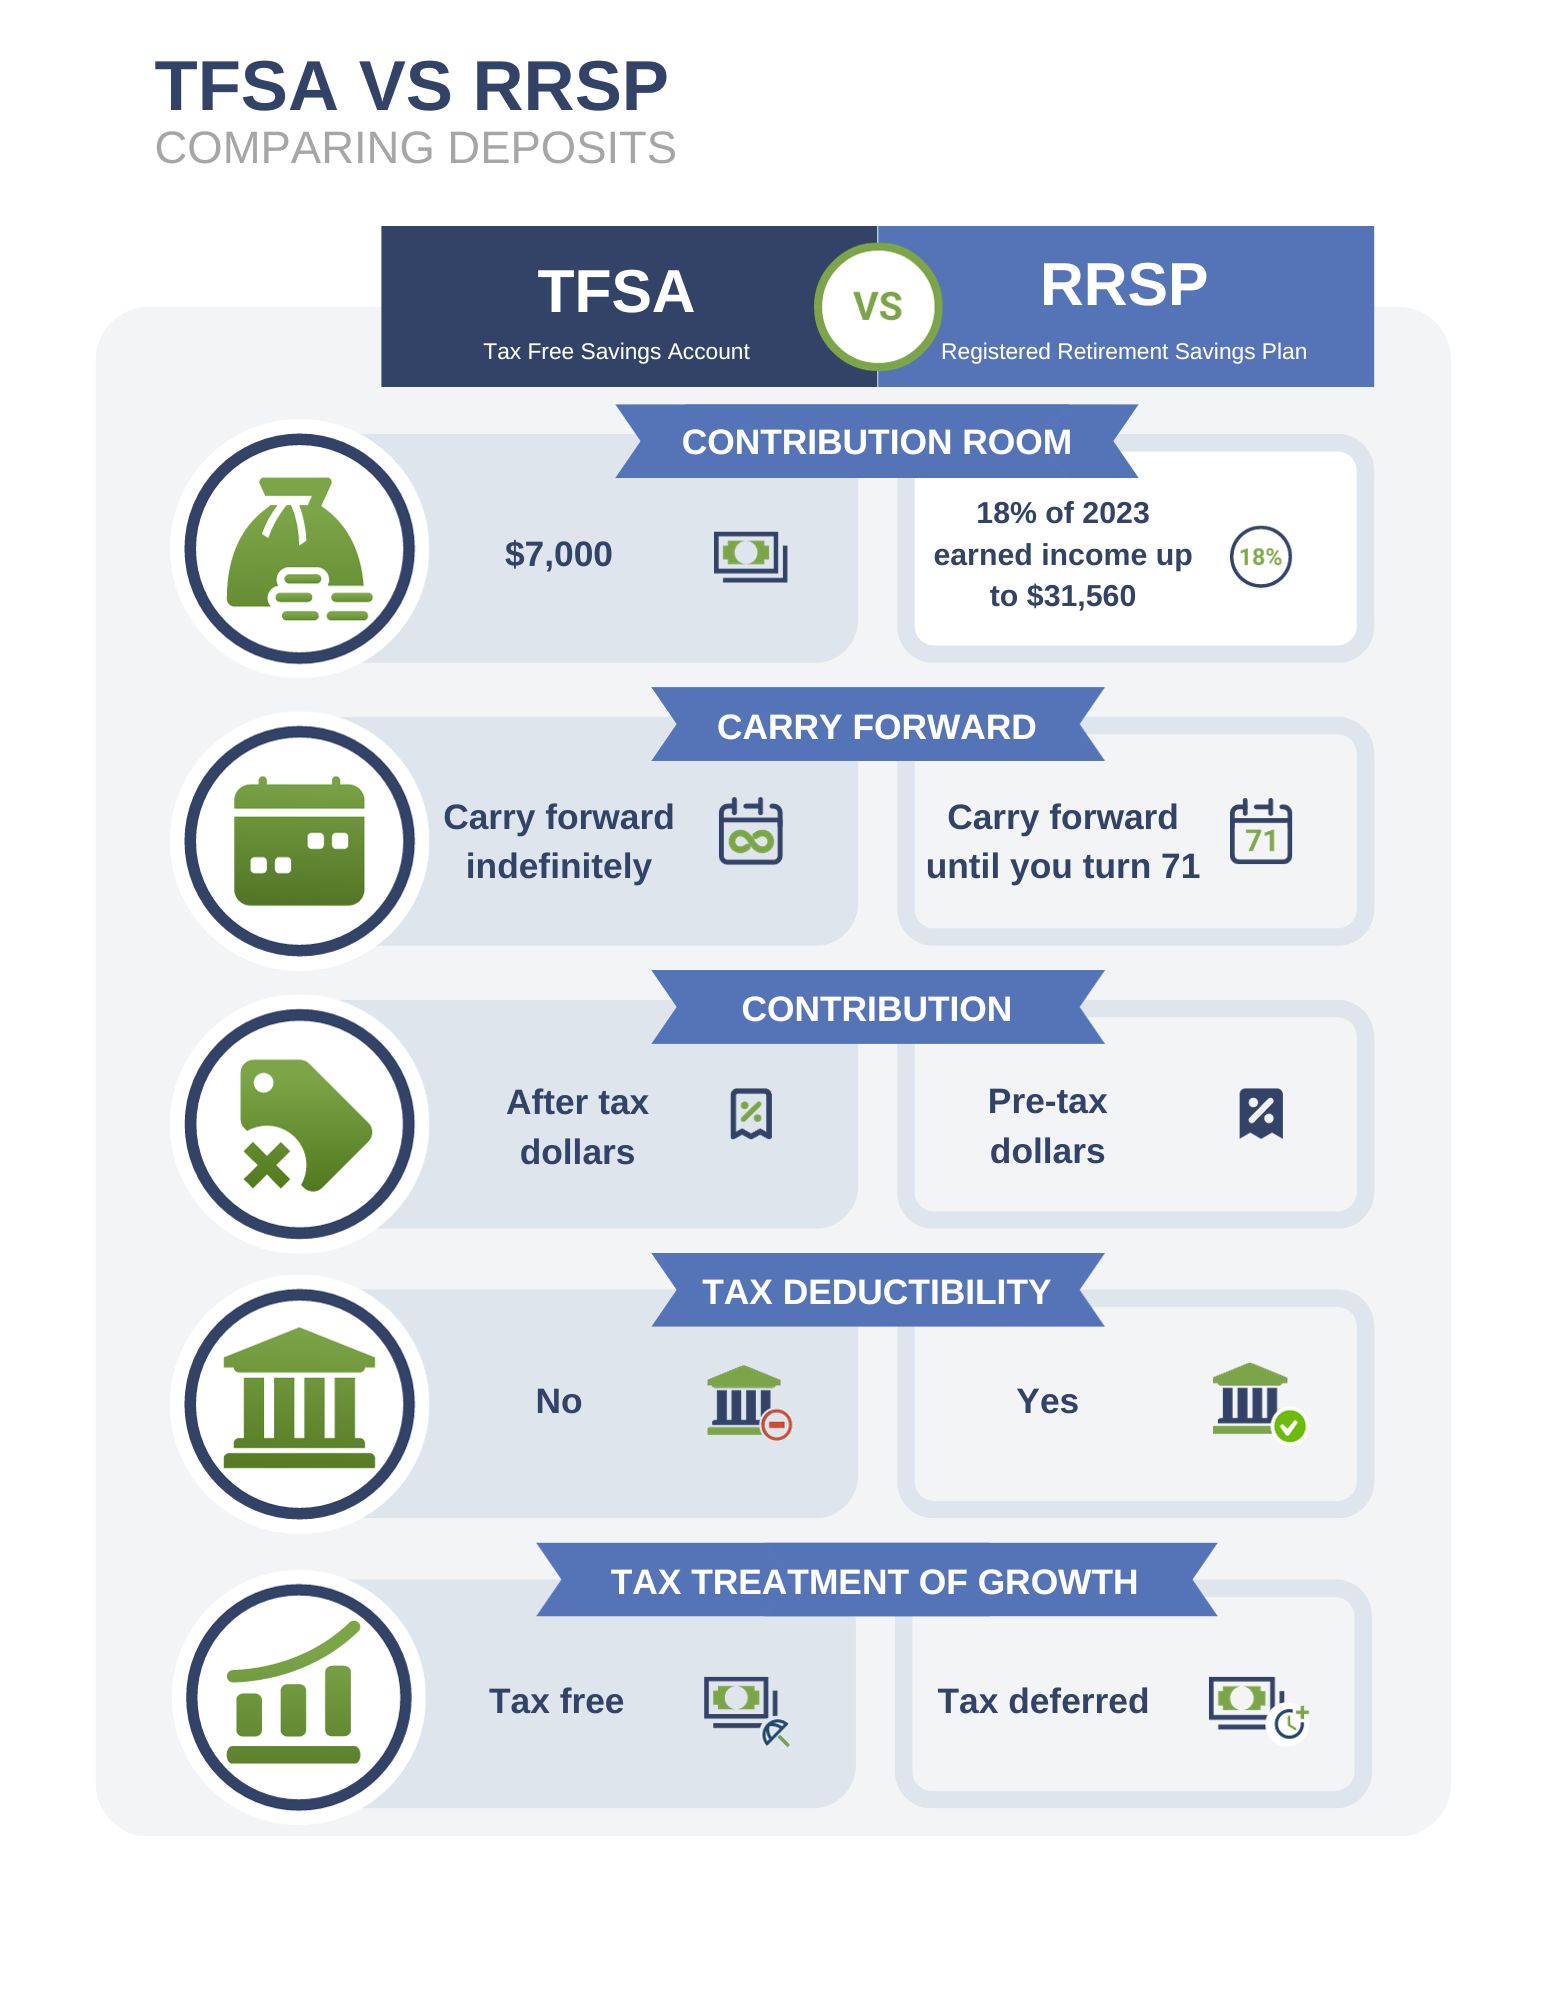
TFSA versus RRSP – Difference in deposits 

When comparing deposit differences between TFSAs and RRSPs, there are several key considerations: 

  • The amount of contribution room available

  • The ability to carry forward unused contributions

  • The tax deductibility of contributions

  • The tax treatment of growth in the account


How much contribution room do I have? 

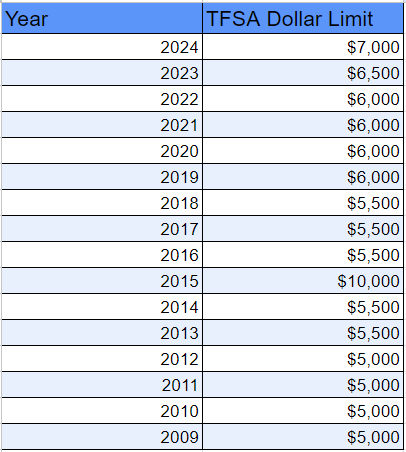
If you have never contributed to a TFSA, you can contribute up to $95,000 today. This table outlines the contribution amount you are allowed each year since TFSAs were created, including this year:
Regarding RRSPs, the limit for tax deductions is 18% of your pre-tax earned income from the previous year, with a maximum limit of $31,560. To illustrate, if your pre-tax income in 2023 was $60,000, your deduction limit for 2024 would be $10,800 (18% x $60,000). If your pre-tax income was $200,000, the maximum limit of $31,560 would apply. 

How much contribution room can I carry forward? 

Suppose you opt not to contribute to your TFSA each year or do not contribute the maximum amount. In that case, you can carry forward your unused contribution room indefinitely, provided you are a Canadian resident, over 18 years of age, and have a valid social insurance number. If you make a withdrawal, the amount withdrawn will be added to your annual contribution room for the next calendar year. 

In contrast, for an RRSP, you can carry forward your unused contribution room until age 71. Once you reach 71, you are required to convert your RRSP into an RRIF. Withdrawals from an RRSP do not create additional contribution room.

The tax deductibility of contributions

Your TFSA contributions are not tax-deductible and are made with after-tax dollars. 

Your RRSP contributions are tax-deductible and made with pre-tax dollars. 

Tax Treatment of Growth 

It is essential to contribute to both RRSP and TFSA because of the different tax treatment of the growth within them. 

A TFSA is ideal for short-term goals, such as saving for a down payment on a house or a vacation, as its growth is entirely tax-free. When withdrawing from your TFSA, you will not have to pay any income tax on the amount withdrawn. On the other hand, the growth within an RRSP is tax-deferred. This means you will not pay taxes on your RRSP gains until age 71, at which point you convert the RRSP into an RRIF and start withdrawing money. 

RRSPs are more suitable for long-term goals such as retirement because, in retirement, you will have a lower income and be in a lower tax bracket, resulting in less tax on your RRIF income.
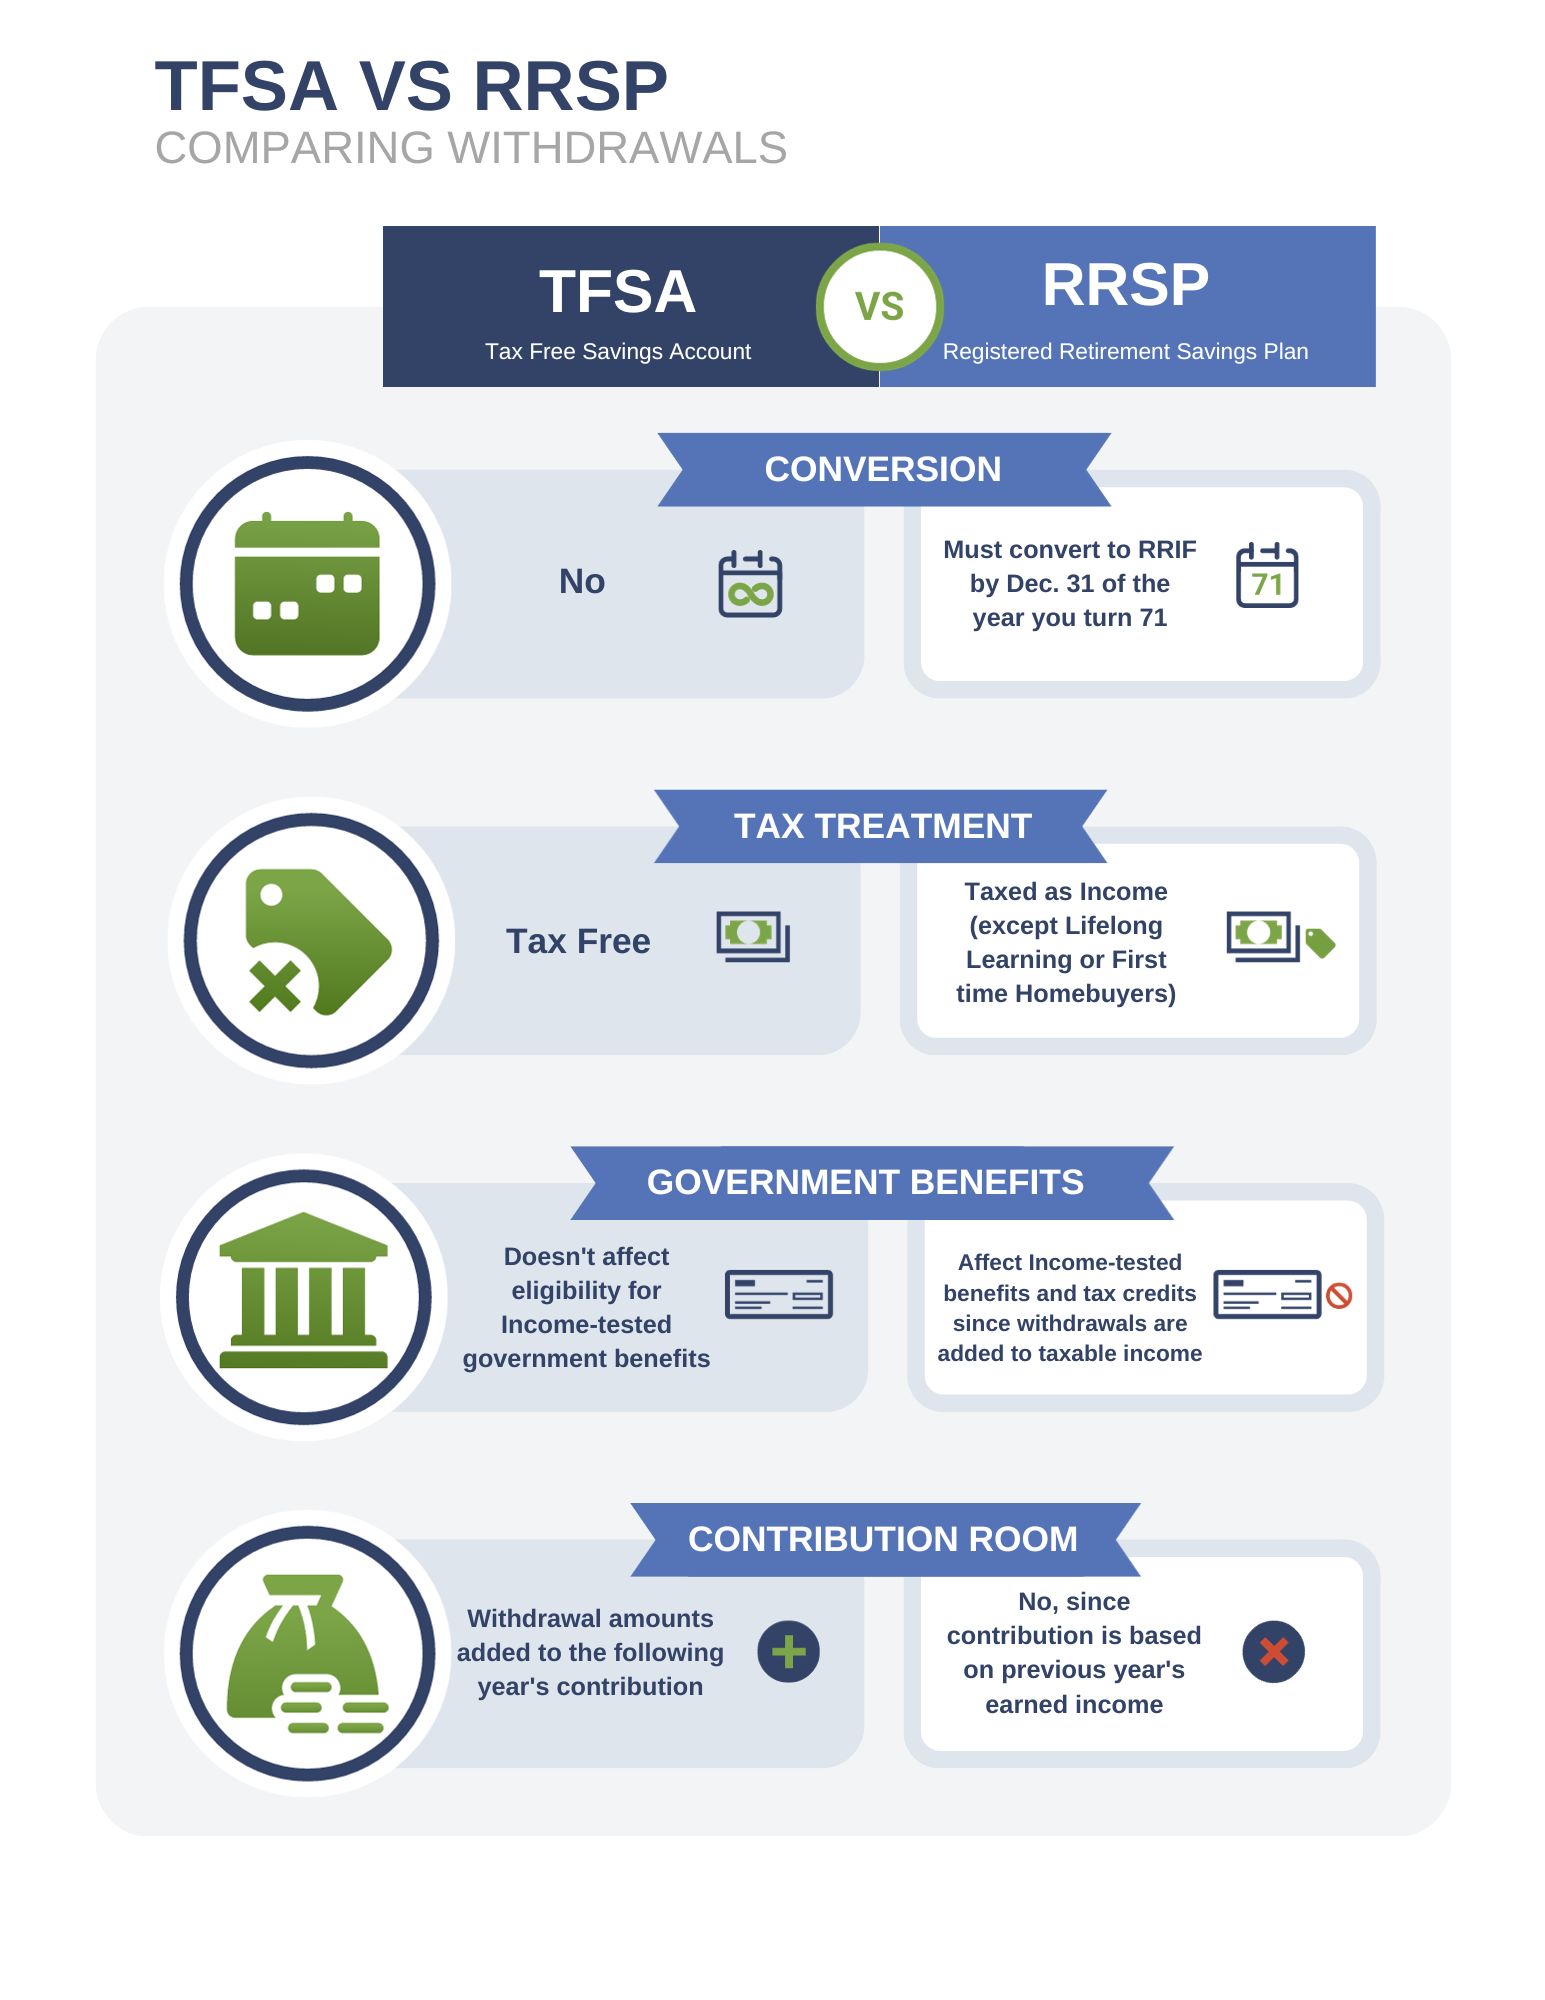
TFSA versus RRSP – Differences in withdrawals 

There are several areas to focus on when comparing differences in withdrawal: 

  • Conversion Requirements 

  • Tax Treatment 

  • Government Benefits 

  • Contribution Room 

Conversion Requirements 

For a TFSA, there are never any conversion requirements as there is no maximum age for a TFSA. 

For an RRSP, you must convert it to a Registered Retirement Income Fund (RRIF) if you turn 71 by December 31st, 2024. 

Tax Treatment of Withdrawals 

One of the most attractive things about a TFSA is that all your withdrawals are tax-free! Therefore, they are recommended for short-term goals; you don’t have to worry about taxes when you take money out to pay for a house or a dream vacation. 

With an RRSP, if you make a withdrawal, it will be taxed as income except in two cases: 

  • The Home Buyers Plan lets you withdraw up to $35,000 tax-free, but you must pay it back within fifteen years. 

  • The Lifelong Learning Plan lets you withdraw up to $20,000 ($10,000 maximum per year) tax-free, but you must pay it back within ten years. 

How will my government benefits be impacted? 

If you are withdrawing from your TFSA or RRSP, it’s essential to know how that will affect any benefits you receive from the government. 

Since TFSA withdrawals are not considered taxable income, they will not impact your eligibility for income-tested government benefits. 

RRSP withdrawals are considered taxable income and can affect the following: 

  • Income-tested tax credits such as Canada Child Tax Benefit, the Working Income Tax Benefit, the Goods and Services Tax Credit, and the Age Credit. 

  • Government benefits including Old Age Security, Guaranteed Income Supplement and Employment Insurance. 

How will a withdrawal impact my contribution room? 

If you withdraw from your TFSA, the amount you withdrew will be added on top of your annual contribution room for the following calendar year. If you withdraw from your RRSP, you do not open any additional contribution room. 

The Takeaway 

RRSPs and TFSAs can both be great savings vehicles. However, there are significant differences between them which can affect your finances. If you need help navigating these differences, please do not hesitate to contact us. We’re here to help.

Latest posts

  • Why a Critical Illness Insurance Top-Up Could Make a Big Difference

    Why a Critical Illness Insurance Top-Up Could Make a Big Difference

    September 1, 2026
  • Financial Checklist for New Parents in Canada

    Financial Checklist for New Parents in Canada

    August 3, 2026
  • How to Catch Up on Your RRSP Contributions

    How to Catch Up on Your RRSP Contributions

    June 30, 2026
  • What Is Participating Whole Life Insurance?

    What Is Participating Whole Life Insurance?

    June 1, 2026
  • Tax-Free Savings Account vs Registered Retirement Savings Plan

    Tax-Free Savings Account vs Registered Retirement Savings Plan

    June 1, 2026

RSS Subscribe via RSS

  • Why a Critical Illness Insurance Top-Up Could Make a Big Difference September 1, 2026
    Many Canadians have some critical illness coverage through work, but it often isn’t enough. A top-up can help families, employees, and business owners bridge the gap, offering peace of mind, flexibility, and protection when it’s needed most.
    Investing with Purpose
  • Financial Checklist for New Parents in Canada August 3, 2026
    A new baby changes everything, including your money. Between sleepless nights and tiny socks, a few financial steps can help protect your growing family. Here is a simple checklist of what to set up, update, and start when a baby joins your home.
    Investing with Purpose
  • How to Catch Up on Your RRSP Contributions June 30, 2026
    Unused RRSP contribution room does not disappear, it carries forward every year. If you have fallen behind on contributions, you may have more room than you realize. Here is how RRSP catch-up contributions work and how to use them to reduce your tax bill
    Investing with Purpose
  • What Is Participating Whole Life Insurance? June 1, 2026
    Participating whole life insurance is a permanent policy that does more than protect your family — it builds cash value and pays dividends over time. Learn how it works, who it's for, and how it compares to other types of life insurance.
    Investing with Purpose
  • Tax-Free Savings Account vs Registered Retirement Savings Plan June 1, 2026
    Tax-Free Savings Accounts (TFSAs) and Registered Retirement Savings Plans (RRSPs) are two of the most effective tools Canadians can use to save tax-efficiently. While TFSAs offer tax-free growth and flexible access, RRSPs provide tax-deductible contributions and tax-deferred growth. Understanding how each account works — and how withdrawals affect taxes and benefits — can help you […]
    Investing with Purpose

Mutual Funds Provided Through Sterling Mutuals Inc.

Insurance products and other related financial services are provided by Adam Aleshka & Investing With Purpose Ltd. as independent insurance agents and are not the business of or monitored by Sterling Mutuals Inc.

Investing With Purpose Ltd.

Adam Aleshka

Financial Advisor

BOOK A MEETING
To book a meeting with Adam please click the button above and book a phone call, virtual appointment or an in person meeting with Adam by accessing his online booking calendar.

The contents of this website do not constitute an offer or solicitation for residents in the United States or any other jurisdiction where Sterling Mutuals is not registered or permitted to conduct business.

Get In Touch



(204) 293-4305



Toll-Free

1-866-519-4301



aaleshka@sterlingmutuals.com



Suite 303 – 400 Wardlaw Avenue
Winnipeg, MB
R3L 0L7

  • Follow

Latest News

Why a Critical Illness Insurance Top-Up Could Make a Big Difference

Many Canadians have some critical illness coverage through work, but it often isn’t enough. A top-up can help families, employees, and business owners bridge the gap, offering peace of mind, flexibility, and protection when it’s needed most.

Financial Checklist for New Parents in Canada

A new baby changes everything, including your money. Between sleepless nights and tiny socks, a few financial steps can help protect your growing family. Here is a simple checklist of what to set up, update, and start when a baby joins your home.

How to Catch Up on Your RRSP Contributions

Unused RRSP contribution room does not disappear, it carries forward every year. If you have fallen behind on contributions, you may have more room than you realize. Here is how RRSP catch-up contributions work and how to use them to reduce your tax bill

What Is Participating Whole Life Insurance?

Participating whole life insurance is a permanent policy that does more than protect your family — it builds cash value and pays dividends over time. Learn how it works, who it’s for, and how it compares to other types of life insurance.

About Us

I think that the advisor/client partnership should be built on more than just “dollars and cents.” I feel as though it should be built upon mutual trust & transparency.  I feel as though the stronger our relationship is, the more likely it is that my clients will achieve their long term financial goals. I am seeking out more than just a typical transactional relationship with the families that I represent. I am seeking out long term partnerships with families committed to their long term financial success.

Legal Information

 Privacy Information

How to Make a Complaint

Investor Protection Corporation

Account Opening Information

2023© Financial Tech Tools Inc.