(204) 293-4305 aaleshka@sterlingmutuals.com
Adam Aleshka
  • HOME
  • ABOUT
    • ABOUT
    • FAQs
    • SUPPLIERS
    • PRIVACY STATEMENT &
      WEBSITE TERMS OF USE
  • SERVICES
    • FINANCIAL ADVICE
    • FINANCIAL ADVICE FOR
      BUSINESS OWNERS
    • FINANCIAL ADVICE FOR
      PROFESSIONALS
    • INSURANCE PLANNING
      • LIFE INSURANCE
      • CRITICAL ILLNESS INSURANCE
    • INVESTMENT PLANNING
      • PLANNING PYRAMID
      • YOUR RETIREMENT GOALS
      • SAVING & INVESTING
      • TFSAs
      • RRSPs
      • RRIFs
      • RESPs
      • FHSAs
      • RDSPs
  • RESOURCES
    • RESOURCES
    • CALCULATORS
    • Client Login
  • CLIENT LOGIN
  • BLOG
  • CONTACT
  • BOOK A MEETING
Select Page

Tax-Free Savings Account vs Registered Retirement Savings Plan

by Investing with Purpose | Jun 1, 2026 | 2026, Blog, Investment, RRSP, Tax Free Savings Account

Tax-Free Savings Account vs Registered Retirement Savings Plan

When it comes to saving in a tax-efficient way, Canadians often ask the same question: Should I use a TFSA or an RRSP?

Both accounts offer valuable tax advantages, but they work differently — and the “right” choice depends on your income, goals, and how you expect to use the money in the future. As advisors, we often help clients understand not just how these accounts work, but how to use them strategically together.

Below, we break down the key differences between TFSAs and RRSPs, focusing on how contributions and withdrawals work — and how those differences can shape your overall plan.

TFSA vs RRSP: Differences in Contributions

When comparing how TFSAs and RRSPs work on the contribution side, there are four main factors we look at with clients:

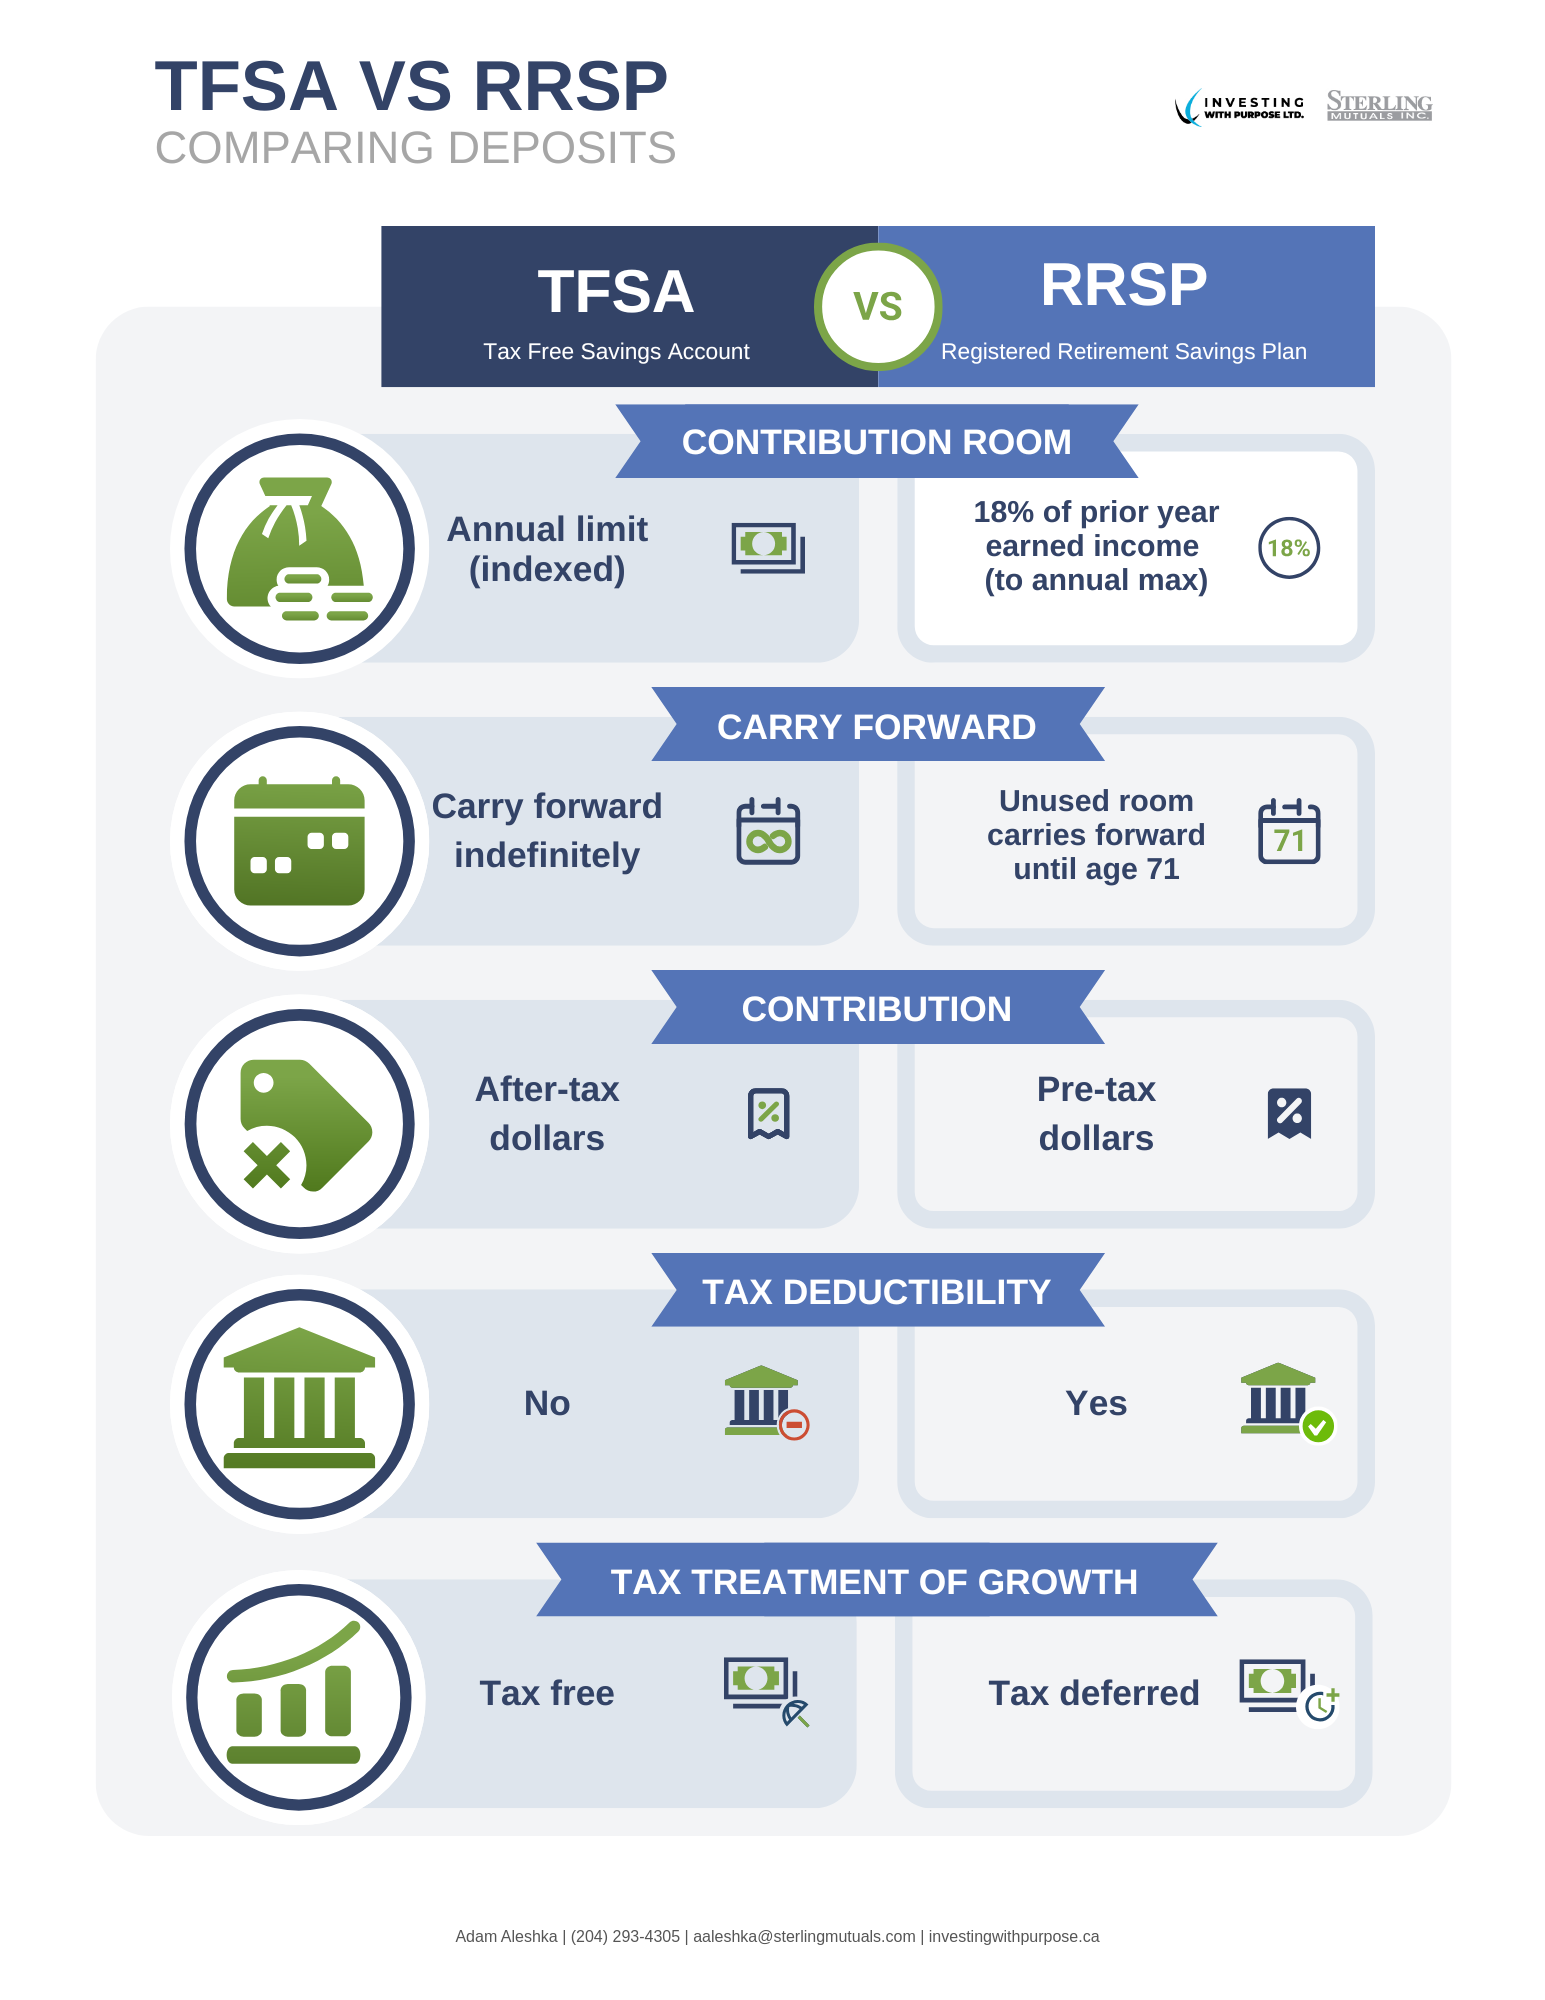
  • Contribution room
  • Carry forward rules
  • Tax deductibility
  • Tax treatment of growth
brandableContent

How much contribution room do you have?

TFSA

Your TFSA contribution room is based on an annual limit set by the federal government, which is indexed and may change over time. If you don’t use your full TFSA room in a given year, the unused amount carries forward and continues to accumulate as long as you’re eligible.

This makes the TFSA especially flexible for people who contribute irregularly or who want to prioritize liquidity.

RRSP

RRSP contribution room is based on your income. Each year, you can contribute up to 18% of your earned income from the prior year, up to an annual maximum set by the Canada Revenue Agency.

Because RRSP room depends on income, contribution limits will naturally vary from person to person.

Can unused contribution room be carried forward?

Yes — for both accounts, but with different rules.

TFSA

Unused TFSA contribution room can be carried forward indefinitely. If you make a withdrawal, the amount withdrawn is added back to your available contribution room in the following calendar year.

RRSP

Unused RRSP contribution room can also be carried forward, but only until the year you turn 71. At that point, your RRSP must be converted to a Registered Retirement Income Fund (RRIF) or another qualifying option. Withdrawals from an RRSP do not create new contribution room.

Are contributions tax-deductible?

This is one of the most important distinctions.

  • TFSA contributions are made with after-tax dollars and are not tax-deductible.
  • RRSP contributions are made with pre-tax dollars and are tax-deductible, which can reduce your taxable income in the year you contribute.

How is investment growth taxed?

  • TFSA growth is completely tax-free. You don’t pay tax on interest, dividends, capital gains, or withdrawals.
  • RRSP growth is tax-deferred. Investments can grow without tax while they remain inside the plan, but withdrawals are taxable when taken.

This difference plays a major role in how each account is used within a broader financial strategy.

TFSA vs RRSP: Differences in Withdrawals

Understanding how withdrawals work is just as important as understanding contributions. When we help clients evaluate withdrawals, we focus on:

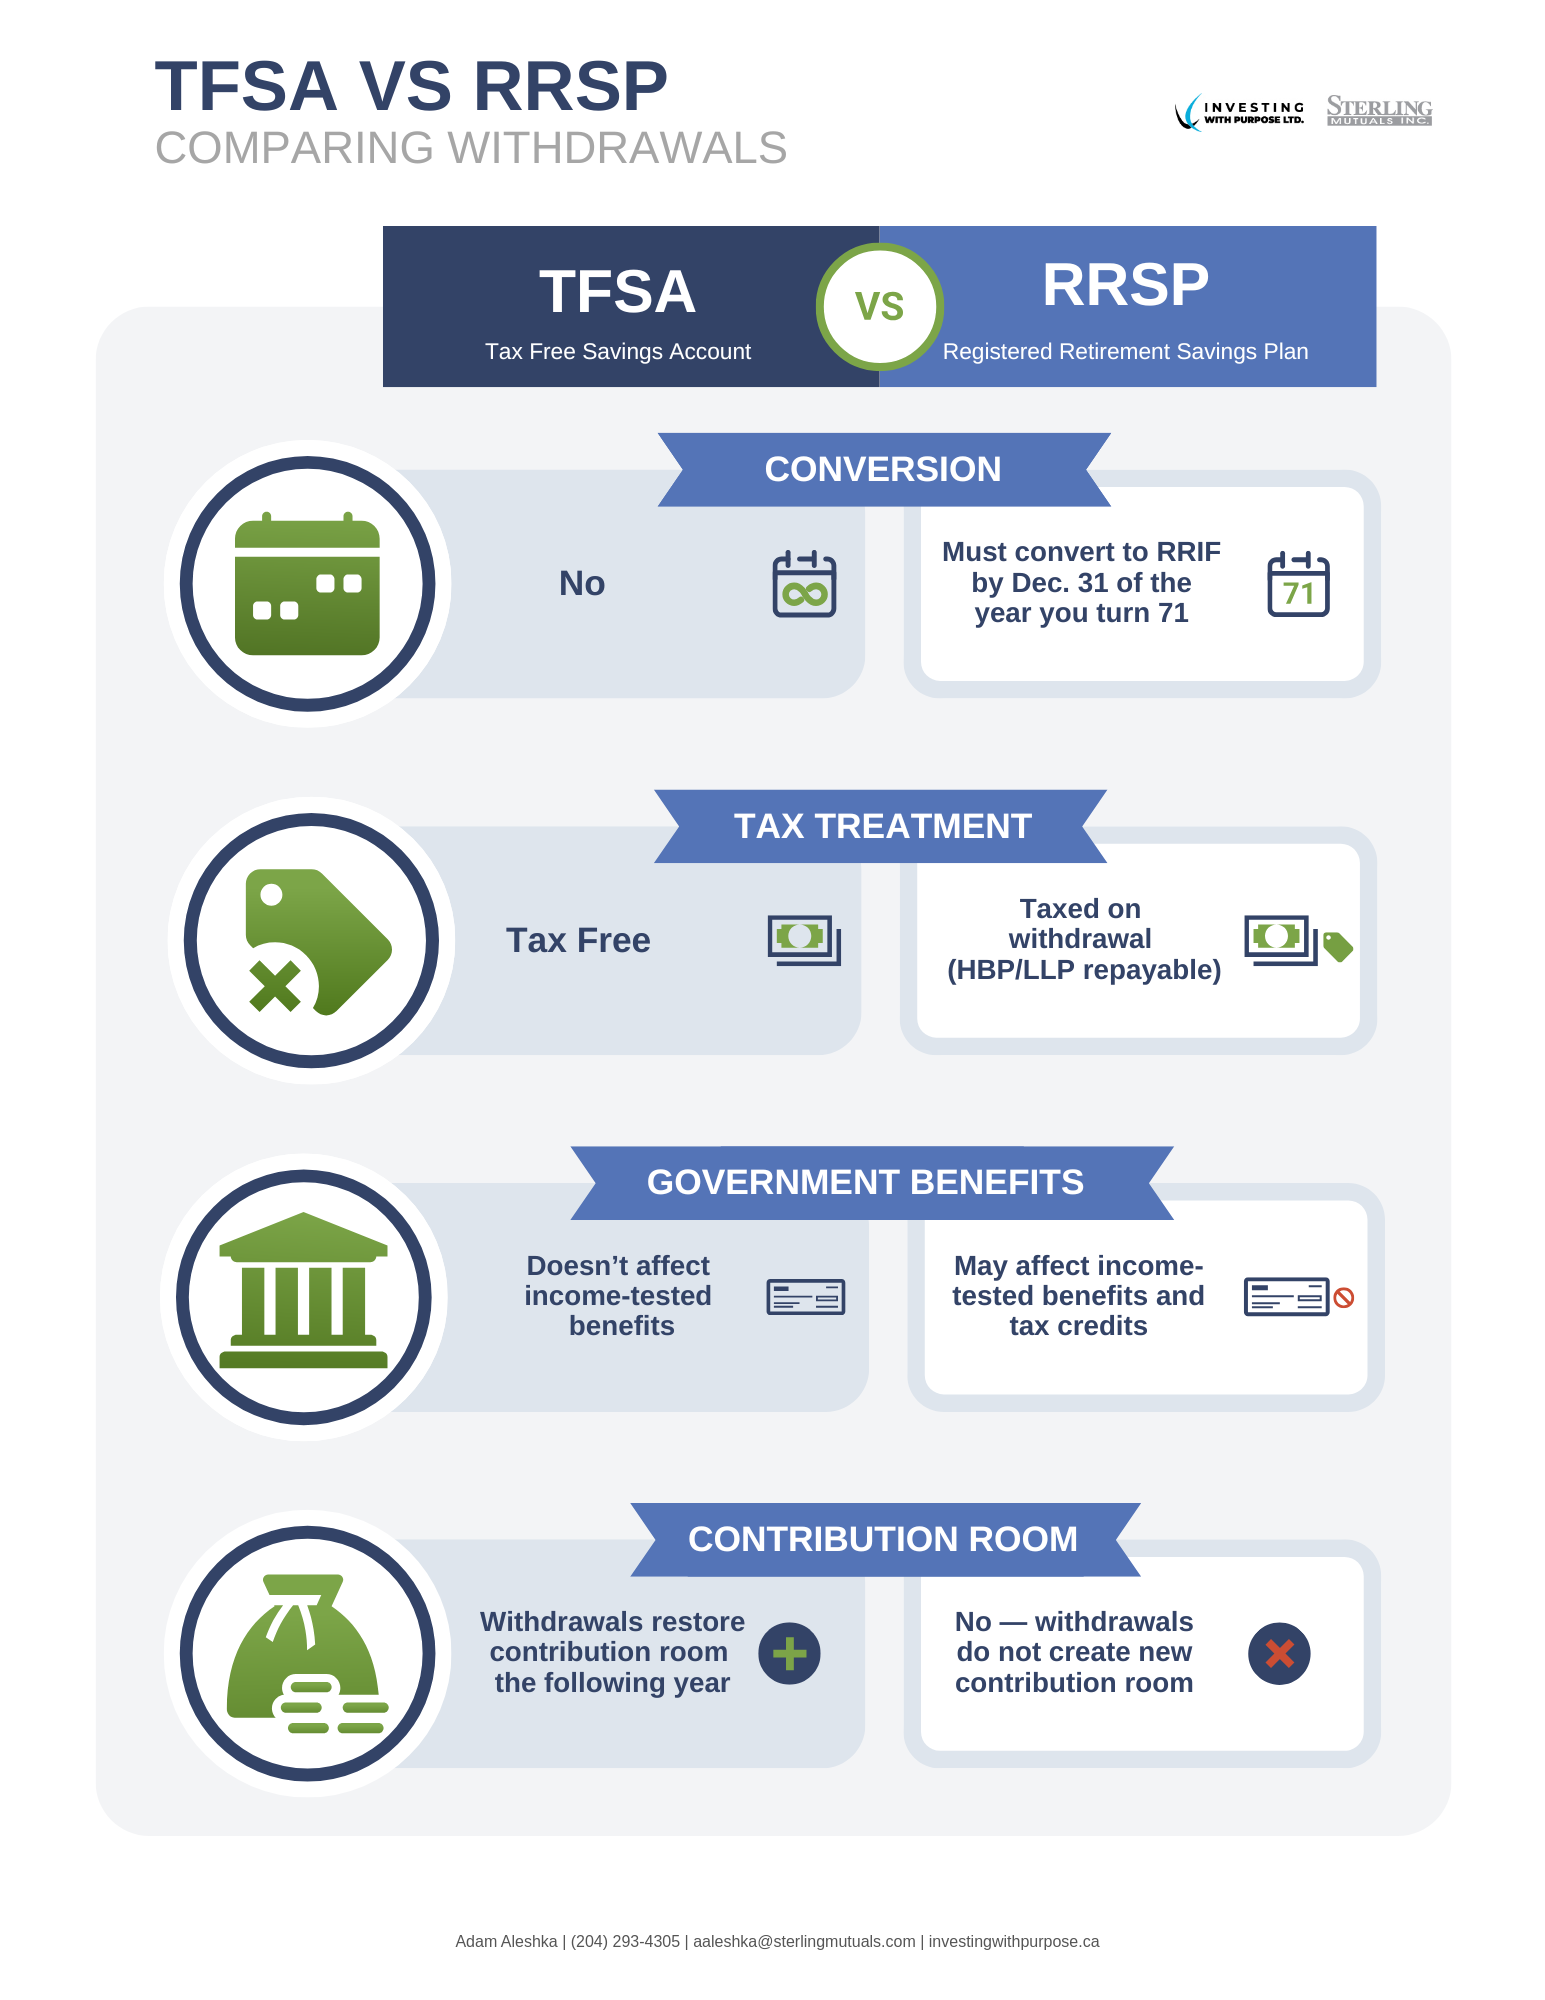
  • Conversion requirements
  • Tax treatment
  • Impact on government benefits
  • Effect on future contribution room
brandableContent

Are there conversion requirements?

TFSA

There are no conversion requirements for a TFSA. You can hold and use a TFSA at any age.

RRSP

An RRSP must be converted to a RRIF (or similar option) by December 31 of the year you turn 71. After conversion, minimum annual withdrawals are required.

How are withdrawals taxed?

TFSA

All TFSA withdrawals are tax-free, regardless of when or why the money is withdrawn.

RRSP

RRSP withdrawals are taxed as income in the year they’re taken.

There are two commonly used programs that allow temporary RRSP withdrawals:

  • The Home Buyers’ Plan (HBP)
  • The Lifelong Learning Plan (LLP)

Withdrawals under these programs are not taxed at the time of withdrawal, provided they are repaid according to the program rules. If they are not repaid, the amounts become taxable income.

How do withdrawals affect government benefits?

This is an area we pay close attention to when planning withdrawals.

  • TFSA withdrawals do not count as taxable income and generally do not affect income-tested government benefits.
  • RRSP (and RRIF) withdrawals are taxable and may affect income-tested benefits and tax credits, depending on your total income.

This distinction often makes TFSAs particularly valuable later in life or during years when benefit eligibility matters.

Do withdrawals create new contribution room?

  • TFSA: Withdrawals restore contribution room in the following calendar year.
  • RRSP: Withdrawals do not create new contribution room.

How advisors typically help clients choose

In practice, the decision isn’t usually TFSA or RRSP — it’s how and when to use each.

We often consider:

  • Current vs future tax rates
  • Income stability
  • Access to employer pension plans
  • Government benefits today or later
  • Short-term flexibility vs long-term tax deferral

Used thoughtfully, both accounts can play an important role in a well-structured plan.

TFSAs and RRSPs are both powerful savings tools, but they’re designed to solve different problems. Understanding how they work — and how they interact with your income, taxes, and benefits — can make a meaningful difference over time.

If you’d like help determining how a TFSA, RRSP, or a combination of both fits into your overall strategy, we’re happy to walk through your options with you.

Sources:

Canada Revenue Agency. Registered Retirement Savings Plan (RRSP). Government of Canada, https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/registered-retirement-savings-plan-rrsp.html

Canada Revenue Agency. Tax-Free Savings Account (TFSA). Government of Canada, https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/tax-free-savings-account.html

Latest posts

  • Why a Critical Illness Insurance Top-Up Could Make a Big Difference

    Why a Critical Illness Insurance Top-Up Could Make a Big Difference

    September 1, 2026
  • Financial Checklist for New Parents in Canada

    Financial Checklist for New Parents in Canada

    August 3, 2026
  • How to Catch Up on Your RRSP Contributions

    How to Catch Up on Your RRSP Contributions

    June 30, 2026
  • What Is Participating Whole Life Insurance?

    What Is Participating Whole Life Insurance?

    June 1, 2026
  • What Is Life Insurance and How Does It Work?

    What Is Life Insurance and How Does It Work?

    May 1, 2026

RSS Subscribe via RSS

  • Why a Critical Illness Insurance Top-Up Could Make a Big Difference September 1, 2026
    Many Canadians have some critical illness coverage through work, but it often isn’t enough. A top-up can help families, employees, and business owners bridge the gap, offering peace of mind, flexibility, and protection when it’s needed most.
    Investing with Purpose
  • Financial Checklist for New Parents in Canada August 3, 2026
    A new baby changes everything, including your money. Between sleepless nights and tiny socks, a few financial steps can help protect your growing family. Here is a simple checklist of what to set up, update, and start when a baby joins your home.
    Investing with Purpose
  • How to Catch Up on Your RRSP Contributions June 30, 2026
    Unused RRSP contribution room does not disappear, it carries forward every year. If you have fallen behind on contributions, you may have more room than you realize. Here is how RRSP catch-up contributions work and how to use them to reduce your tax bill
    Investing with Purpose
  • What Is Participating Whole Life Insurance? June 1, 2026
    Participating whole life insurance is a permanent policy that does more than protect your family — it builds cash value and pays dividends over time. Learn how it works, who it's for, and how it compares to other types of life insurance.
    Investing with Purpose
  • Tax-Free Savings Account vs Registered Retirement Savings Plan June 1, 2026
    Tax-Free Savings Accounts (TFSAs) and Registered Retirement Savings Plans (RRSPs) are two of the most effective tools Canadians can use to save tax-efficiently. While TFSAs offer tax-free growth and flexible access, RRSPs provide tax-deductible contributions and tax-deferred growth. Understanding how each account works — and how withdrawals affect taxes and benefits — can help you […]
    Investing with Purpose

Mutual Funds Provided Through Sterling Mutuals Inc.

Insurance products and other related financial services are provided by Adam Aleshka & Investing With Purpose Ltd. as independent insurance agents and are not the business of or monitored by Sterling Mutuals Inc.

Investing With Purpose Ltd.

Adam Aleshka

Financial Advisor

BOOK A MEETING
To book a meeting with Adam please click the button above and book a phone call, virtual appointment or an in person meeting with Adam by accessing his online booking calendar.

The contents of this website do not constitute an offer or solicitation for residents in the United States or any other jurisdiction where Sterling Mutuals is not registered or permitted to conduct business.

Get In Touch



(204) 293-4305



Toll-Free

1-866-519-4301



aaleshka@sterlingmutuals.com



Suite 303 – 400 Wardlaw Avenue
Winnipeg, MB
R3L 0L7

  • Follow

Latest News

Why a Critical Illness Insurance Top-Up Could Make a Big Difference

Many Canadians have some critical illness coverage through work, but it often isn’t enough. A top-up can help families, employees, and business owners bridge the gap, offering peace of mind, flexibility, and protection when it’s needed most.

Financial Checklist for New Parents in Canada

A new baby changes everything, including your money. Between sleepless nights and tiny socks, a few financial steps can help protect your growing family. Here is a simple checklist of what to set up, update, and start when a baby joins your home.

How to Catch Up on Your RRSP Contributions

Unused RRSP contribution room does not disappear, it carries forward every year. If you have fallen behind on contributions, you may have more room than you realize. Here is how RRSP catch-up contributions work and how to use them to reduce your tax bill

What Is Participating Whole Life Insurance?

Participating whole life insurance is a permanent policy that does more than protect your family — it builds cash value and pays dividends over time. Learn how it works, who it’s for, and how it compares to other types of life insurance.

About Us

I think that the advisor/client partnership should be built on more than just “dollars and cents.” I feel as though it should be built upon mutual trust & transparency.  I feel as though the stronger our relationship is, the more likely it is that my clients will achieve their long term financial goals. I am seeking out more than just a typical transactional relationship with the families that I represent. I am seeking out long term partnerships with families committed to their long term financial success.

Legal Information

 Privacy Information

How to Make a Complaint

Investor Protection Corporation

Account Opening Information

2023© Financial Tech Tools Inc.